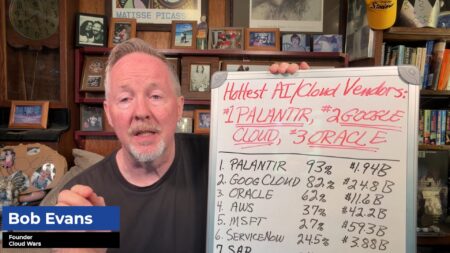
Booming global demand for AI services and innovation has pushed the Cloud Wars Top 10 Growth Chart into unprecedented territory with Palantir holding the #1 spot with a quarterly growth rate of 93%, Google Cloud grabbing the #2 slot with 82%, and Oracle taking #3 with 62%.
Along with those gaudy growth rates for their most-recent quarters — and you can see a detailed breakout for all of the Cloud Wars Top 10 companies in the table below — each of those three ultra-hypergrowth leaders is also on a steep acceleration trajectory with at least three straight quarters of rising growth rates. And for #1 Palantir, that acceleration extends back to its past 12 quarters.
As is always the case when I post these periodic updates to the Cloud Wars Growth Chart, some folks will see fit to say that it is “easy” for companies with relatively “small” revenue bases to grow more rapidly than companies with large revenue bases. And in return, I’ll offer my classic rejoinder: Yes, we all learned that numerical construct back in fourth or fifth grade, so let’s use look beyond the obvious and dig into what’s powering this latest installment in the greatest growth market the world has ever known.
Toward that end, here are a few broad perspectives before I share the latest version of the Cloud Wars Top 10 Growth Chart:
- Each of the hyperscalers has a backlog of at least $500 billion, with the RPO for Microsoft and Oracle each approaching $700 billion.
- While massive contracts with OpenAI and Anthropic certainly make up big portions of those backlog/RPO totals, my guess is they account for 35% to 40% of those totals. That’s certainly a heavy concentration, but it is nothing close to the cataclysmic overdependence that has spooked so many “experts.”
- Despite Satya Nadella’s apocalyptic forecast of the collapse of the enterprise apps business, the rise of Agentic AI has not torpedoed the apps market — and kudos to customers for seeing through Nadella’s glom and doom, and to the software vendors that have raced to make the case for the enhanced value that apps plus agents will have.
- Models are fantastic but platforms are the true foundations of the AI Economy as several of the Cloud Wars Top 10 are creating opportunities for customers to build new capabilities and extend existing ones in ways that would have seemed utterly impossible just a couple of years ago.
- The pace of change — and not just the speed at which the business-tech landscape is changing but the unprecedented intensity of those upheavals — has never been greater and is requiring leaders to structure their organizations differently, deploy speed as the ultimate competitive weapon, and fuse flexibility with unmatched insights in entirely new ways.
No other industry in the world is driving rates of growth like the ones shown below — and when we see Growth Chart leaders Palantir and Google Cloud hit 93% and 82% growth rates as part of accelerating trajectories, then a question that would have seemed absurd just a year ago suddenly becomes quite rational: in the next couple of quarters, will we see a Cloud Wars Top 10 vendor (or two) generate year-over-year quarterly growth of 100% or more?
CLOUD WARS TOP 10 GROWTH CHART: Oct. 1, 2026
| Rank | Company | Cloud Rev. Growth | Quarterly Cloud Rev. | Quarter Ended |
|---|---|---|---|---|
| 1 | Palantir | 93% | $1.94 billion | 6/30 |
| 2 | Google Cloud | 82% | $24.8 billion | 6/30 |
| 3 | Oracle | 62% | $11.6 billion | 8/31 |
| 4 | AWS | 37% | $42.2 billion | 6/30 |
| 5 | Microsoft | 27% | $59.3 billion | 6/30 |
| 6 | ServiceNow | 24.5% | $3.88 billion | 6/30 |
| 7 | SAP | 24% | $7.2 billion | 6/30 |
| 8 | Workday | 14% | $2.47 billion | 7/31 |
| 9 | Salesforce | 11% | $11.3 billion | 7/31 |
| 10 | OpenAI (estimated) | — | $8.7 billion | 8/31 |
Final Thought
About that estimate for OpenAI: It is the only Cloud Wars Top 10 company that is not publicly traded and as such is not required to disclose financial details. But over the past few days, there’s been a lot of chatter about OpenAI having achieved a total annualized run-rate of $70 billion.
Some people I know and trust have told me that the enterprise business has been growing more rapidly than the consumer business and now accounts for about 50% of that total. So, I’ve pegged that portion at about $35 billion, yielding an estimated quarterly enterprise-revenue figure of $8.7 billion. Again — that’s purely a guess, but one that I hope is well-informed.